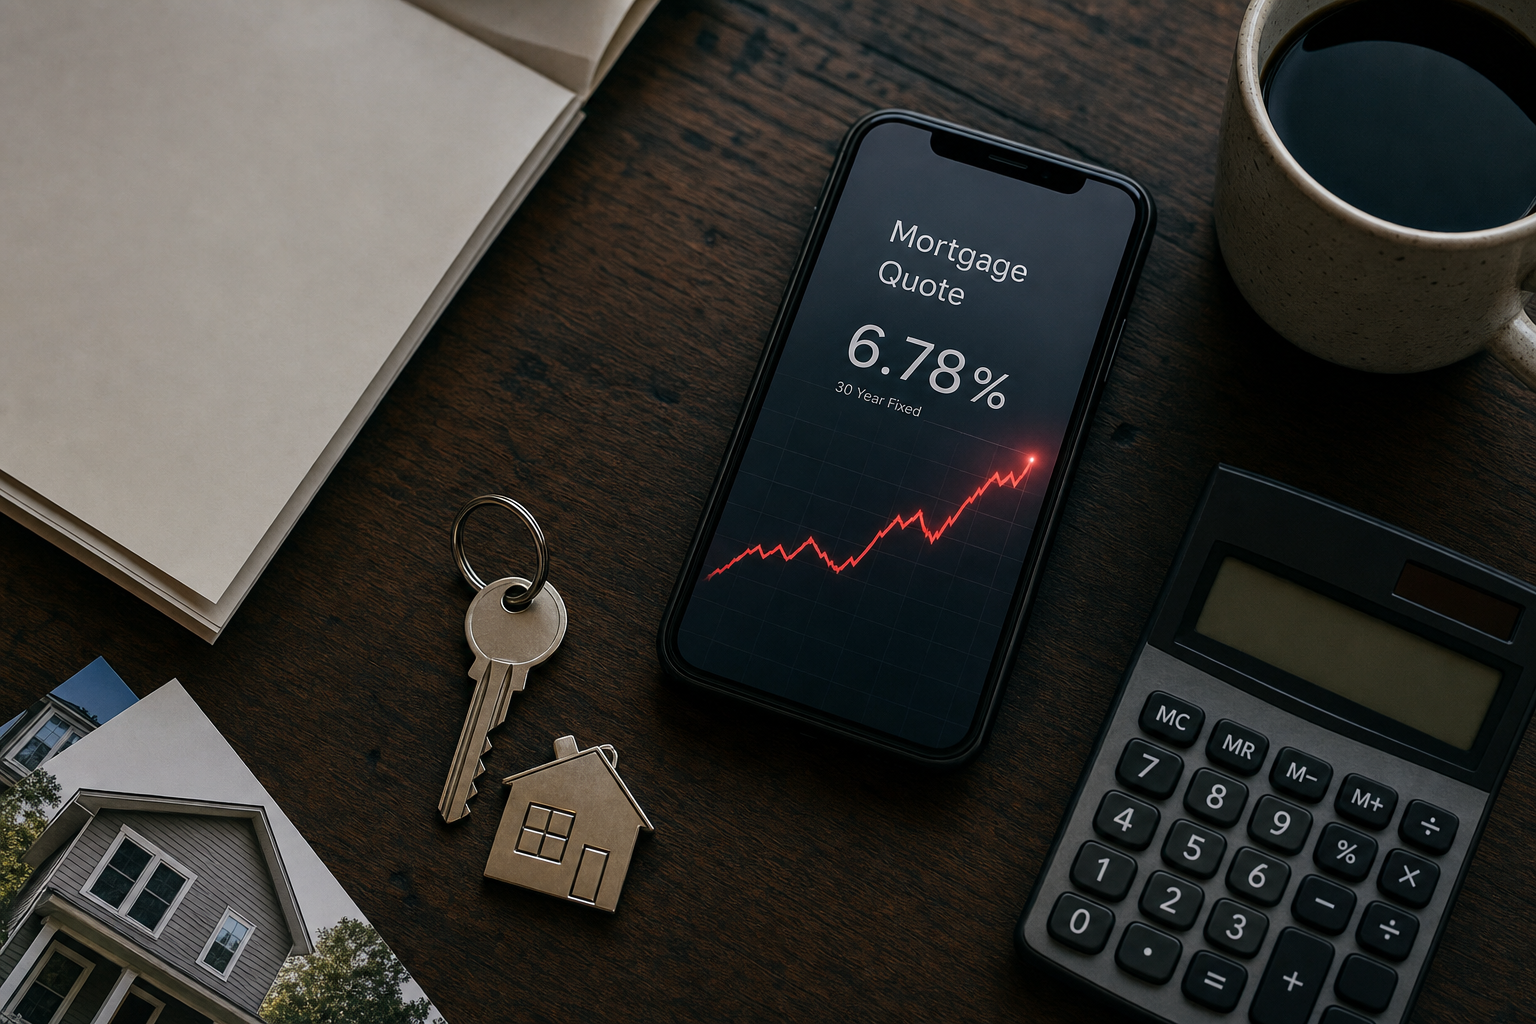
The average 30-year mortgage rate has climbed to 6.66%, its highest level in a year. That does not mean every buyer is boxed in—it means the loan strategy matters more than the listing crush.
The rate story is blunt
The average 30-year U.S. mortgage rate has risen to 6.66%, the highest level in a year, after four straight weekly increases. That turns small price differences into real monthly-payment differences, especially when insurance, taxes, repairs, and moving costs are already crowding the budget.
- Do not anchor your search to last month’s payment math.
- Refresh preapproval numbers before making an offer.
- If a listing needs repairs, price the mortgage and the work together.
Signal Snapshot: Rate Pressure and Policy Mood
The market is not flashing easy-mode: mortgage rates are at a yearly high while the Fed remains cautious.
The Fed is not handing buyers a shortcut
The Federal Reserve held rates steady for the fifth straight meeting. That matters because the Fed’s benchmark rate influences many consumer borrowing costs, including mortgages, credit cards, auto loans, and savings yields. The signal is mixed: the central bank paused, but three policymakers voted to raise rates.
- A pause is not the same thing as relief.
- Mortgage rates can stay stubborn even when the Fed does nothing.
- Build your plan around today’s quote, not a hoped-for cut.
An ARM is a tool, not a loophole
Adjustable-rate mortgages can start with a lower interest rate, which is why they get attention when fixed rates feel heavy. But the reset is the risk. If the rate adjusts before your income, refinance plan, or sale timeline works out, the payment can move against you.
- Ask what the payment could become after the reset.
- Stress-test the loan before accepting the lower starting rate.
- Use an ARM only when the exit plan is realistic, not wishful.
Your lender choice is part of the price
A bank and a credit union may look similar from the outside, but the mortgage experience can differ. The useful move is not picking a team in advance; it is making both compete on the same loan amount, rate type, fees, timing, and service expectations.
- Request comparable quotes on the same day when possible.
- Compare more than the headline rate.
- Ask how quickly the lender can move once you are under contract.
What to do before you fall for the house
In a squeezed market, the cleanest advantage is preparation. Know the payment ceiling, know the reset risk, and know which lender can actually close. The house can be emotional; the financing should be almost boring.
- Set a monthly-payment limit before touring.
- Keep a fixed-rate quote and an ARM quote in view if both are viable.
- Re-check debt costs, since the Fed’s benchmark can touch more than mortgages.
Related Moea features
Download Moea to use these features in the app. They help turn the day's market signals into saved searches, payment checks, tours, and deeper research when you are ready to act.
Test a home price against today’s rate pressure before you tour.
Calculate paymentLine up bank and credit union offers without losing the real cost in the fine print.
Compare lendersWritten with Daft AI from today's real-estate signals, market reporting, and Moea context. It is here to help you spot the shape of the day, not replace your own diligence; details can shift, and even smart models can miss nuance.