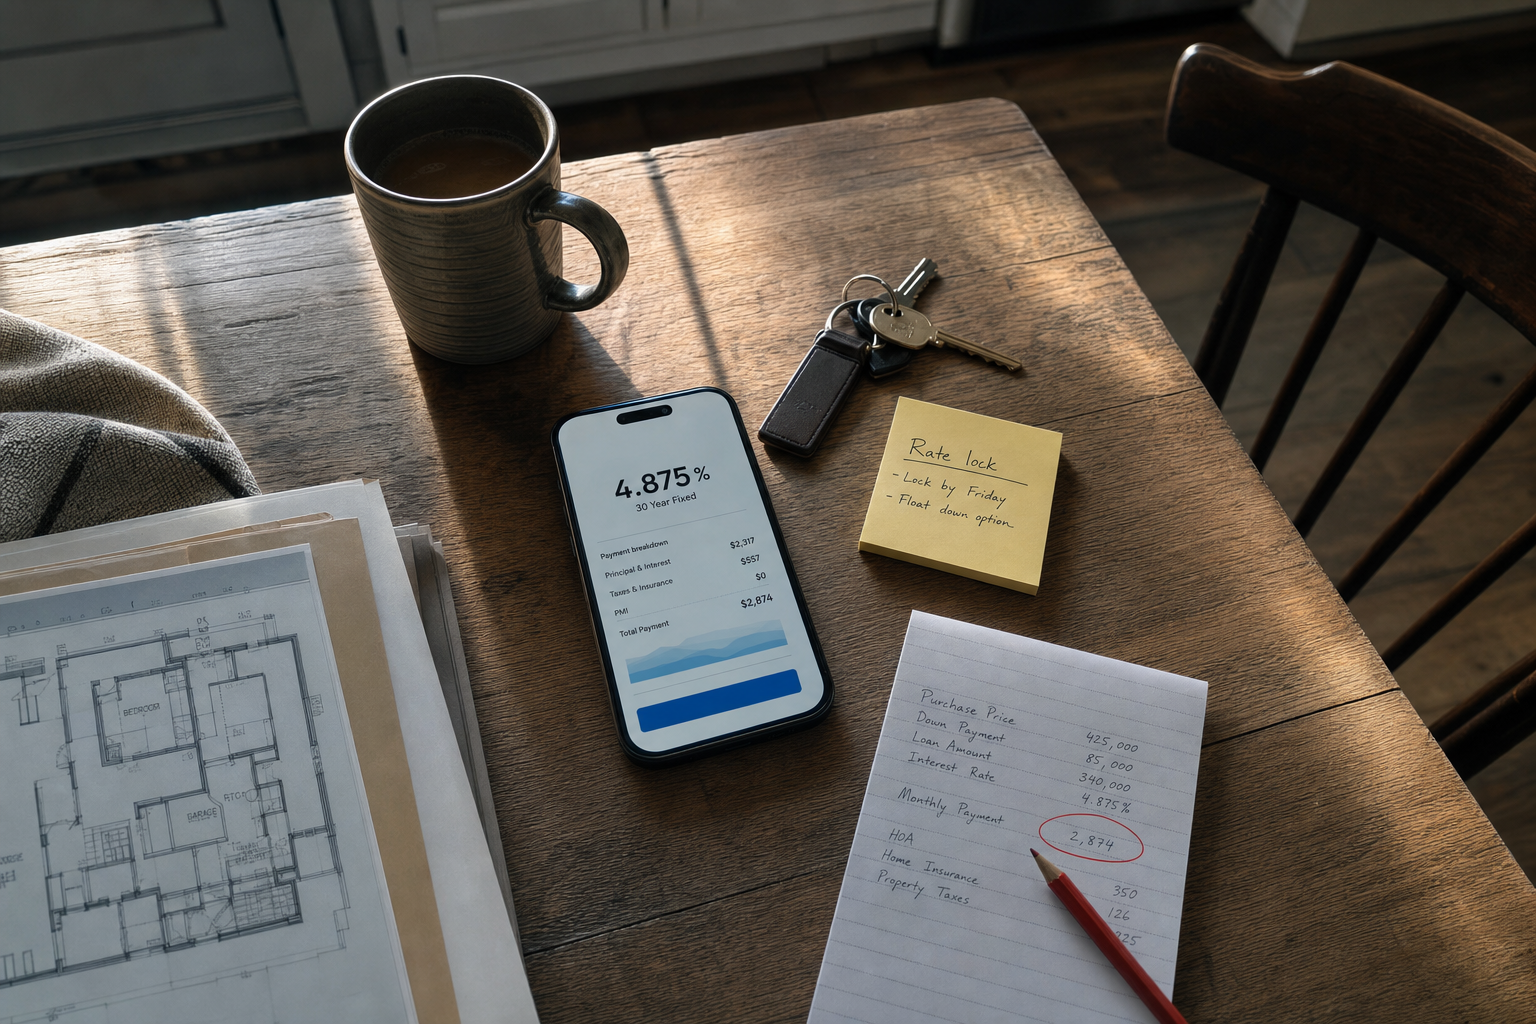
Hotter inflation reports pushed mortgage rates to their highest point since March, while a separate read showed rates at a five-week high. That sounds like a deal-killer. It has not been one yet: mortgage applications stayed in positive territory, a sign that some buyers are still moving when the home, payment, and timing line up.
Signal Snapshot
The market’s main character this week is the monthly payment. Mortgage rates jumped after hotter-than-expected inflation reports, reaching the highest level since March. Another read described rates as the highest in five weeks. Either way, the direction is clear: financing got less forgiving.
- Higher rates do not just raise the payment; they shrink the margin for inspection fixes, appraisal gaps, and stretch offers.
- A rate move can turn a comfortable search into a narrow one without the listing price changing at all.
- If your preapproval is more than a couple of weeks old, treat it like a draft, not a promise.
Signal Snapshot: Equity Cost
The average HELOC rate cited for May 15 sits above the comfort zone for casual borrowing.
Buyers did not vanish
The surprising part: buyers did not all step back. Even with mortgage rates climbing, stronger demand helped keep mortgage applications in positive territory. That does not mean the market is easy. It means motivated buyers are still sorting through the noise, especially when a listing is priced cleanly or solves a specific life problem.
- Do not assume every competing buyer disappeared because rates rose.
- Do watch stale listings; sellers may become more flexible if higher rates thin the showing traffic.
- If a home checks the right boxes, speed still matters — but only after the payment math survives stress testing.
Signal Notes: Rate Pressure
The week’s signal is a mix of higher borrowing costs and still-active demand.
Equity is useful, not magic
For owners thinking about using home equity to renovate, consolidate debt, or help fund the next move, the rate backdrop matters too. The average HELOC rate cited for May 15 was 7.21%. The Yahoo Finance report also notes why equity borrowing can run higher than purchase-loan pricing: lenders are taking on different risk.
- A HELOC can add flexibility, but the rate deserves the same scrutiny as a mortgage quote.
- Compare the monthly cost of borrowing against the value of the project or strategy it supports.
- Do not treat equity as free cash just because it is already in the house.
The move-before-you-move checklist
This is a market for boring discipline. Before falling in love with a kitchen island, run the payment at today’s quote, then run it again with a cushion. Ask your lender how long the quote holds, what a lock costs, and how points change the break-even timeline. If you are selling and buying, price the current home with urgency in mind, not fantasy math from a lower-rate month.
- Refresh your preapproval before touring seriously.
- Set a top payment number, not just a top purchase price.
- Ask for seller credits where the listing has sat, but do not build your entire plan around getting them.
- Keep cash buffers intact; higher rates make surprise repairs feel louder.
Bottom line
Rates are applying pressure, but the market is not frozen. The useful signal is not “buy now” or “wait forever.” It is this: if the payment works under today’s tougher terms, you are negotiating from reality. If it only works with a lower rate, a perfect seller concession, and no surprises, it is not a plan yet.
- Rates are applying pressure, but the market is not frozen.
- The useful signal is not “buy now” or “wait forever.” It is this: if the payment works under today’s tougher terms, you are negotiating from reality.
Related Moea features
Download Moea to use these features in the app. They help turn the day's market signals into saved searches, payment checks, tours, and deeper research when you are ready to act.
Stress-test a home price against today’s rate before you tour.
Open calculatorTrack homes that sit longer and may invite sharper negotiation.
Set alertsWritten with Daft AI from today's real-estate signals, market reporting, and Moea context. It is here to help you spot the shape of the day, not replace your own diligence; details can shift, and even smart models can miss nuance.