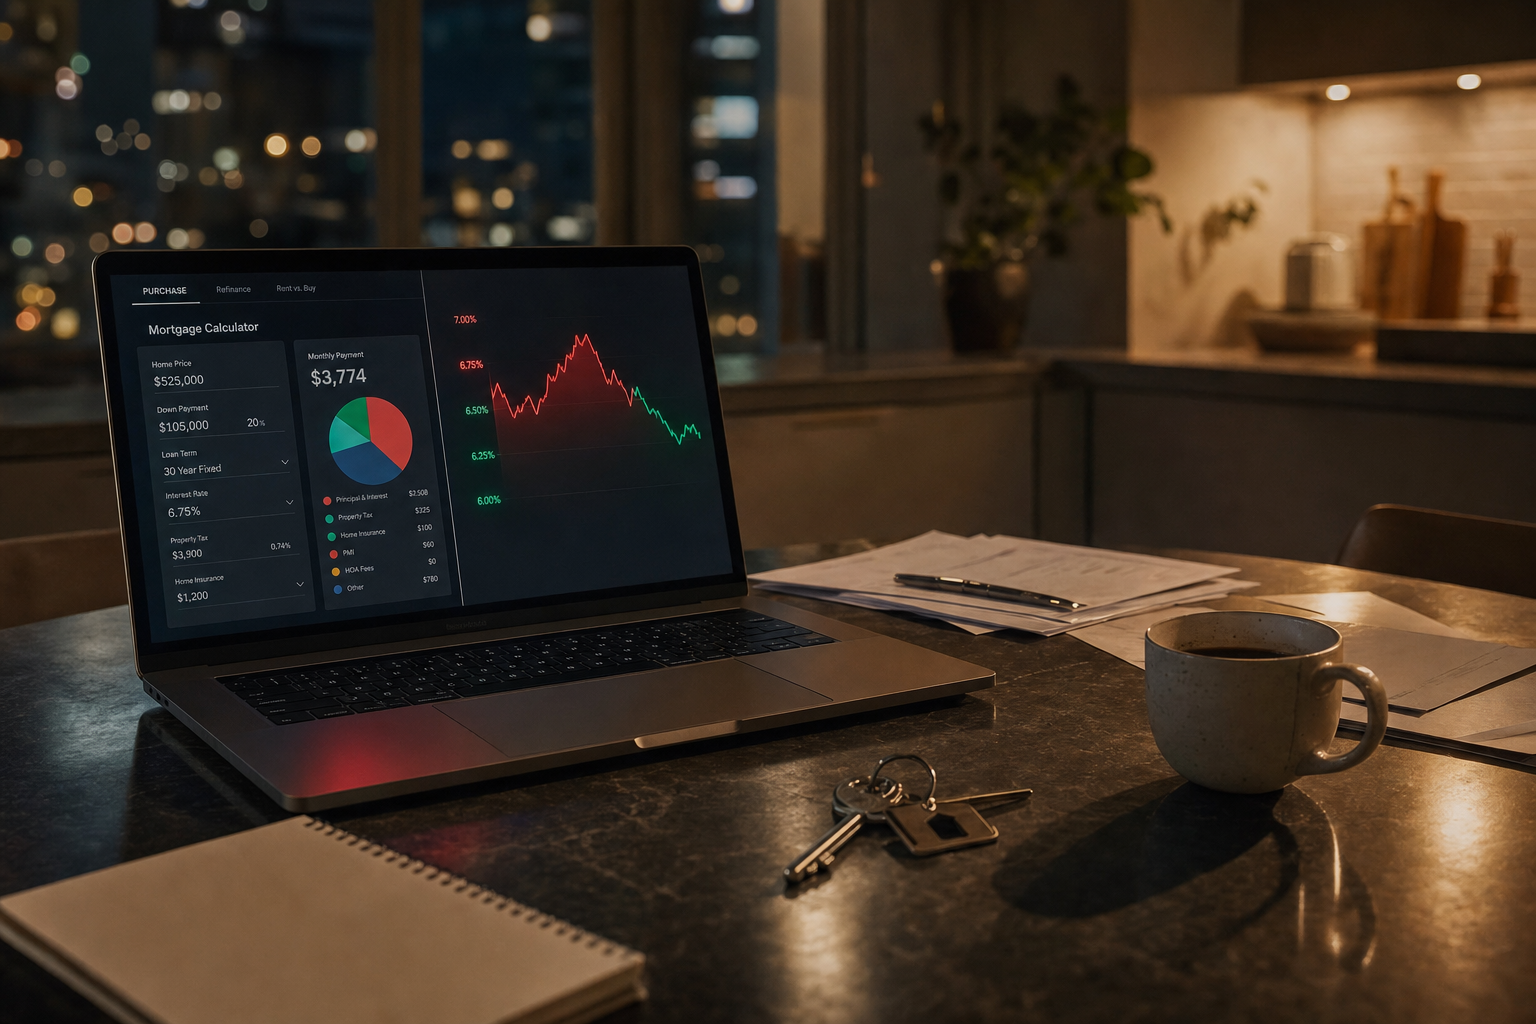
The weekly mortgage-rate headline looks friendlier: rates eased again and recently sat just below 6.5%. But the bigger affordability picture turned worse for the first time since 2023, with borrowing costs eating more of household earnings. Translation: a tiny rate dip helps, but it does not reset the math. The smarter move is to shop the loan, stress-test the payment, and treat every “great offer” like a draft—not a deal.
The headline dip is not the whole story
Mortgage rates easing for a second week sounds like oxygen. It is—but only a little. The average long-term U.S. mortgage rate moved down, while separate reporting showed rates recently hovering just below 6.5%. At the same time, a U.S. affordability gauge worsened for the first time since 2023 as borrowing costs claimed a bigger share of earnings.
- Do not read a rate dip as a green light by itself.
- Watch the payment-to-income picture, not just the quoted rate.
- If the payment only works under perfect conditions, it probably does not work.
Signal Notes: Rate Pressure
The mortgage-rate story is mixed: a recent dip helps, but the level is still elevated and affordability has moved the wrong way.
The Fed risk is still in the room
The market is not moving in a straight line. Fed minutes showed growing support for a rate hike by September, and mortgage activity is already feeling the squeeze. Bond-market stress also matters because mortgage pricing tends to react when investors demand higher yields. That is why one calm week can be followed by a jumpy quote sheet.
- Get quotes close together so lenders are competing in the same market window.
- Ask how long a rate lock lasts and what it costs.
- If you are stretching, volatility is not background noise—it is part of the price.
Signal Snapshot: Cash Context
The down payment is only one cash line; the real decision includes closing costs, reserves, and the loan offer’s fine print.
A bank offer is a starting point, not a finish line
Banks know when you are likely to need a mortgage, and their offers can feel personalized enough to skip the hunt. Don’t. A familiar logo is not the same thing as the best total cost. Compare rate, points, lender fees, credits, lock terms, and estimated cash to close before you attach your emotions to a property.
- Ask each lender for the same loan scenario so the comparison is clean.
- Separate the lowest monthly payment from the lowest total cost.
- If one offer looks weirdly good, make the lender explain every fee and assumption.
The down payment is your pressure valve
A down payment is the portion of the purchase price you pay upfront. Simple definition, big consequences. More cash down can reduce the loan amount, but using too much cash can leave you house-rich and life-poor. The right number is not just what gets you approved; it is what leaves enough room for repairs, moving costs, and a boring-but-vital emergency buffer.
- Model at least two down-payment scenarios before picking a price range.
- Keep closing costs separate from your down-payment number.
- Do not drain every account just to make the offer look cleaner.
Bottom line: buy the math, not the mood
This is a market where tiny improvements can feel bigger than they are. Rates eased, yes. Affordability still worsened. Mortgage demand has stalled, and policy risk has not disappeared. If a home fits your life and the numbers survive a tougher rate quote, keep moving. If the deal only works because you are hoping next week gets easier, wait for better math.
- Green flag: the payment works even with conservative assumptions.
- Yellow flag: the deal depends on one lender’s teaser-like quote.
- Red flag: you have no cash cushion after closing.
Related Moea features
Download Moea to use these features in the app. They help turn the day's market signals into saved searches, payment checks, tours, and deeper research when you are ready to act.
Line up lender quotes side by side before a familiar bank offer becomes your default.
Compare offersCheck whether the monthly number still works if rates or fees move against you.
Run the testWritten with Daft AI from today's real-estate signals, market reporting, and Moea context. It is here to help you spot the shape of the day, not replace your own diligence; details can shift, and even smart models can miss nuance.