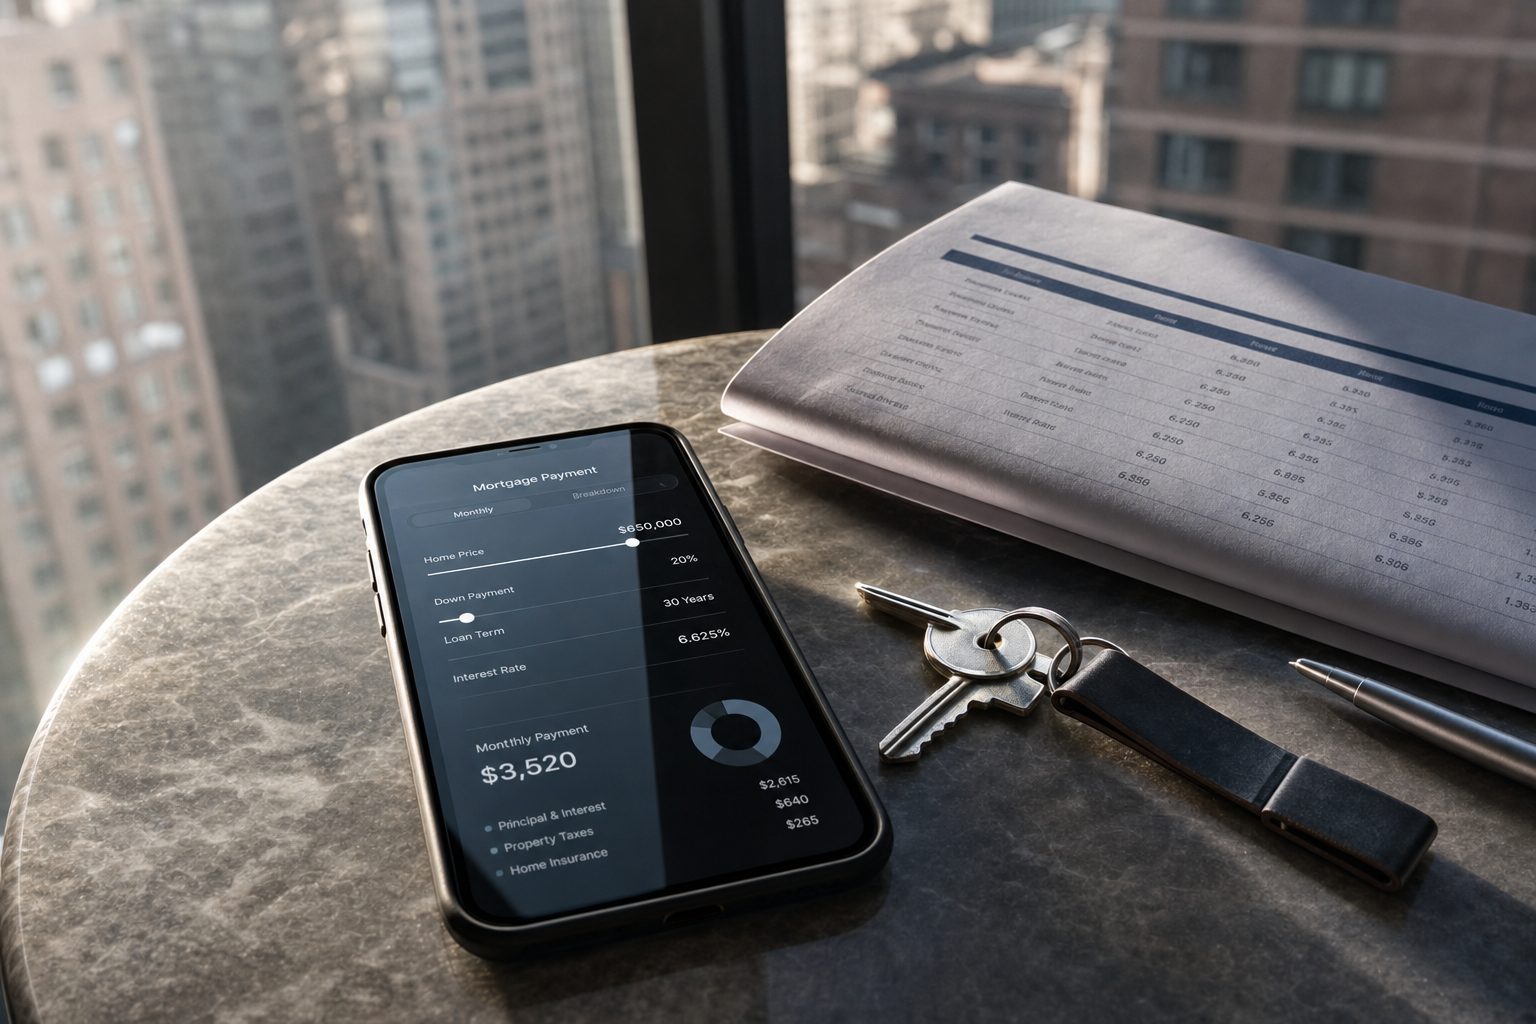
The 30-year mortgage average rose to 6.66%, its highest level in a year, while the Fed held steady and home-equity borrowing stayed sticky. Translation: the market is not handing buyers relief. The move now is sharper math, cleaner tradeoffs, and fewer rushed yeses.
The rate headline is simple. The strategy is not.
A 6.66% average 30-year mortgage rate is not just a headline number. It changes how far each dollar goes, how much negotiating power matters, and how quickly a “maybe” home can become a hard no. Because the increase marks the fourth straight weekly rise and the highest level in a year, buyers should treat every quote as perishable.
- Ask lenders for same-day estimates so comparisons are clean.
- Price the monthly payment first, then back into the home price.
- If a seller offers a credit, test whether it helps more as a rate buydown or closing-cost relief.
Signal Comparison: Borrowing Costs
The HELOC average sits above the 30-year mortgage average, while the HELOC low shows how narrow recent relief has been.
The Fed pause is not a green light
The Fed held its benchmark rate unchanged, but that does not mean mortgage rates automatically relax. The benchmark touches many consumer rates directly or indirectly, and markets still react to inflation pressure, growth expectations, and lender risk. In plain English: waiting only works if your plan has a trigger, not a wish.
- Set a rate ceiling before touring seriously.
- Know the payment where you pause the search.
- Keep savings liquid; a tighter credit market rewards clean files.
Home equity money is not cheap money
For owners trying to renovate, consolidate debt, or solve a life transition, home equity borrowing still needs caution. The average HELOC adjustable rate was 7.23%, barely above its 2026 low of 7.19%. That tiny gap may feel reassuring, but adjustable debt can still move, and borrowing against the house adds pressure to the asset you sleep in.
- Use a HELOC when flexibility matters more than certainty.
- Use a fixed home-equity loan when payment stability matters more than draw flexibility.
- Do not raid retirement money to force a housing solution without modeling the long-term cost.
What to do before you make an offer
This is a market for boring discipline. The winning move is not predicting the perfect rate dip. It is building an offer that survives a rate bump, an inspection surprise, and a lender re-check.
- Run the payment at today’s quoted rate and a slightly worse one.
- Compare at least three lenders before choosing the house emotionally.
- Ask your agent to identify listings where seller credits are more likely than price cuts.
- Keep a walk-away number in writing before negotiations start.
The bottom line
Rates are doing what they do best: making everyone recalculate. That does not kill the search. It just moves the advantage toward buyers and owners who can separate the home they want from the financing structure they can live with.
- The house is the emotional decision; the loan is the survival plan.
- A good deal should still look good after the payment math.
Related Moea features
Download Moea to use these features in the app. They help turn the day's market signals into saved searches, payment checks, tours, and deeper research when you are ready to act.
Stress-test a home price against today’s rate before you tour.
Calculate monthly costTrack listings where financing concessions may matter more than a small price cut.
Create alertWritten with Daft AI from today's real-estate signals, market reporting, and Moea context. It is here to help you spot the shape of the day, not replace your own diligence; details can shift, and even smart models can miss nuance.